When a Higher Offer Pays Less: Net Proceeds vs Offer Price for Sellers
Net proceeds are the cash you actually get at closing. The offer price is only the headline number, and the two can differ by tens of thousands of dollars. Net proceeds equals sale price minus mortgage payoff, agent commissions, and closing costs. The biggest deductions usually come from the loan balance and the commission split. Before you accept anything, run the net proceeds calculation on every offer you get, not just the one with the highest number on top.
TL;DR:
- Running a detailed ledger for each offer helps accurately compare net proceeds, accounting for payoffs, commissions, closing costs, credits, and prorations.
- Using the lender’s actual payoff quote avoids discrepancies that can inflate the mortgage payoff and significantly reduce net proceeds.
- Concessions, credits, and holdbacks can offset higher offer prices, sometimes making a lower offer more profitable after deductions.
- Net proceeds are crucial for estimating potential capital gains taxes, so modeling this figure helps prevent unexpected IRS liabilities.
- Comparing offers based on net proceeds and closing speed, rather than price alone, leads to selecting the strongest deal overall.
Table of Contents
- Net Proceeds vs Offer Price: What Each Number Actually Means
- How to Calculate Net Proceeds Step by Step
- A Worked Example: Two Offers, Same House, Different Outcomes
- What Deductions Typically Cost You
- How Offer Terms Quietly Erode Your Proceeds
- How Net Proceeds Affect Your Tax Bill
- How to Compare Competing Offers the Right Way
- Run the Exact Numbers Before You Sign Anything
- Sources Worth Checking
- FAQ
Net Proceeds vs Offer Price: What Each Number Actually Means
The offer price, also called the contract price or asking price, is the dollar figure a buyer agrees to pay for the house. It is the number in the purchase agreement, and it is the number most sellers fixate on. It tells you nothing about what lands in your bank account.
Gross proceeds is the sale price at closing, before subtracting anything. Net proceeds is what remains after the title company pays off the mortgage, the commissions, the closing costs, and any credits owed to the buyer. That figure is your take-home cash.
Net proceeds is not the same as profit. Profit, or capital gain, subtracts your adjusted basis (what you paid for the house plus qualifying improvements) from net proceeds. A seller can have healthy net proceeds and still owe capital gains tax, or have low net proceeds and no tax at all. Keep the two separate.
The number that matters shifts as the deal moves. At the offer stage, you are estimating net proceeds off a rough mortgage balance. Under contract, you refine it with actual quotes. At closing, the settlement statement locks in the real figure. Update your math at each stage, not just once.
How to Calculate Net Proceeds Step by Step
The formula is straightforward:
Net proceeds = sale price − mortgage and lien payoffs − agent commissions − seller closing costs − seller credits ± prorations and adjustments
Run it as a ledger, not a mental estimate. Every offer gets the same line items:
- Sale price. The contract price from the accepted offer.
- Mortgage and lien payoffs. Any first mortgage, second mortgage, HELOC, or judgment lien attached to the property.
- Agent commissions. Listing and buyer-agent fees, typically split and paid from proceeds at closing.
- Seller-paid closing costs. Title insurance, escrow fees, transfer taxes, recording fees, and attorney fees where applicable.
- Seller credits and concessions. Repair credits, closing cost assistance, or rate buydowns you agreed to cover.
- Prorations and adjustments. Property taxes, HOA dues, and utilities split between buyer and seller based on the closing date.
One detail trips up more sellers than any other: use the lender’s actual payoff quote, not your last mortgage statement. A payoff quote includes accrued interest through the closing date and any reconveyance fees. Your account balance does not. That gap alone can run into the hundreds of dollars, and it grows if closing gets pushed back.
A Worked Example: Two Offers, Same House, Different Outcomes
Say a house is under contract at $350,000. Here’s the ledger from contract price to net proceeds:
- Sale price: $350,000
- Mortgage payoff: $210,000
- Agent commissions (5%): $17,500
- Seller closing costs (title, escrow, transfer tax): $6,000
- Prorations (property tax credit to buyer): $1,200
- Net proceeds: $115,300
That’s an 8.5-point drop from headline price to take-home cash, before any concessions enter the picture. On a typical sale, expect the gap between offer price and net proceeds to be a significant portion once commissions, payoff costs, and prorations are counted.
Now compare two competing offers on that same house.
Scenario A: $360,000 offer with a $10,000 seller credit toward the buyer’s closing costs and a $5,000 repair credit after inspection. Net proceeds drop to roughly $110,300.
Scenario B: $345,000 offer, no concessions, clean inspection. Net proceeds land near $115,800.
The lower offer nets more. Mortgage payoff and commissions are the two line items that swing hardest. Concessions come in third, and they’re the one variable buyers use to make a weaker offer look stronger on paper.
What Deductions Typically Cost You
Commissions are usually the single largest deduction. Total commission runs in a broad range depending on how the listing agent and buyer’s agent split it, and buyer-agent compensation terms have shifted in recent years, so confirm the exact split in your listing agreement before you count on a number.
Beyond commissions, expect these categories on nearly every sale:
- Title and escrow fees, covering the title search, title insurance policy, and closing/escrow service.
- Transfer and recording taxes, set by your state or county and based on sale price.
- Attorney fees, required in some states and optional in others.
- Courier and payoff processing fees, charged by the lender to release the lien.
Then there are the deductions sellers forget to model until they see the settlement statement:
- Prorated property taxes and HOA dues, credited to the buyer for the days the seller still technically owned the home in that billing period.
- Unpaid utility balances or municipal liens, which title companies catch and deduct automatically.
- Escrow holdbacks, where a portion of proceeds is held back until a repair or condition is satisfied post-closing.
- Repair credits negotiated after inspection, which reduce your check dollar-for-dollar even though they never touch the contract price.
None of these show up in the number a buyer writes on their offer sheet. They show up on the closing disclosure, usually with little warning if you haven’t modeled them ahead of time.
How Offer Terms Quietly Erode Your Proceeds
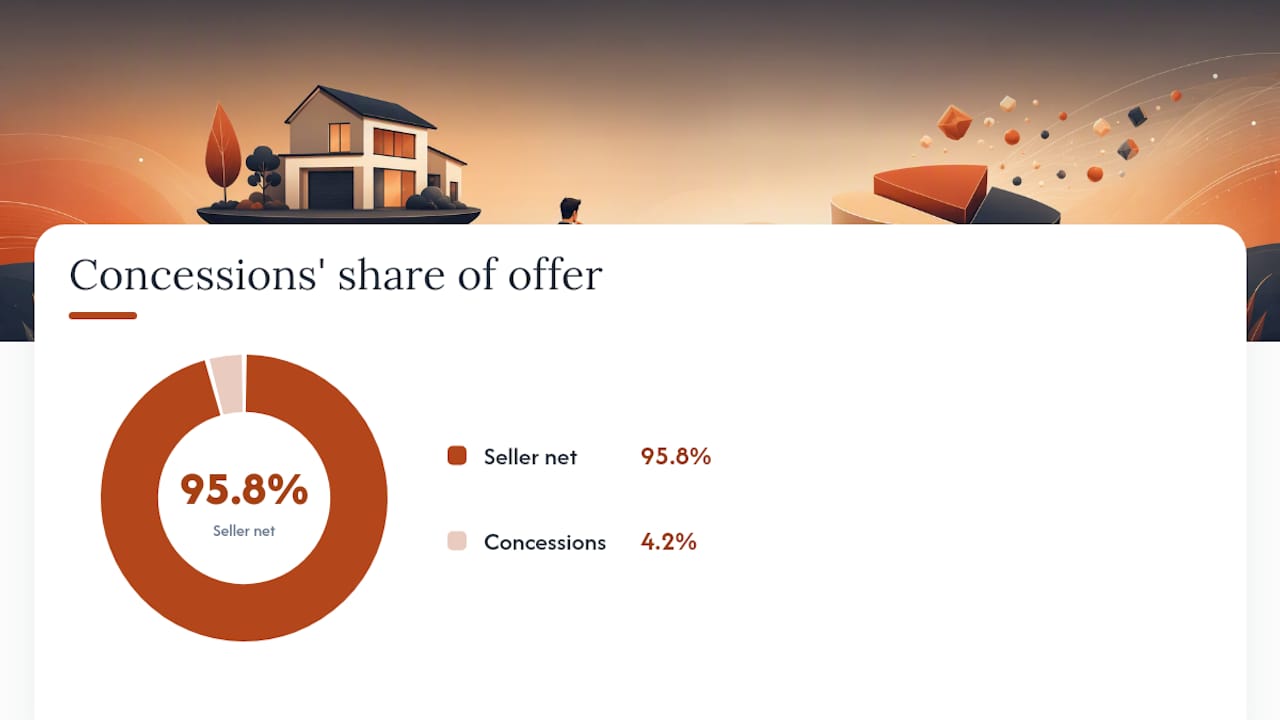
A higher offer price can net you less if it carries bigger concessions. Seller credits, repair allowances, and rate buydowns all come straight out of proceeds, dollar for dollar. A $360,000 offer with a $15,000 credit package nets the same as a $345,000 offer with none. Buyers know this, and some structure offers to look strong on price while shifting cost back onto the seller after inspection.
Watch for these terms specifically:
- Escrow holdbacks for incomplete repairs, which delay part of your cash past the closing date.
- Post-closing true-ups, where a final proration adjustment settles after the fact.
- Earnest money handling, which affects timing more than the total, but matters if a deal falls through.
To compare offers fairly, normalize the assumptions. Use the same commission rate, the same closing date for prorations, and the same estimated repair cost across every offer you evaluate. Only then does the price difference mean anything.
Pro Tip: Before accepting an offer with an unusual credit or concession, ask the buyer’s agent for an itemized breakdown of what that credit covers. A vague “$10,000 toward closing costs” can hide a repair number that should have been negotiated separately.
How Net Proceeds Affect Your Tax Bill
Capital gains tax is calculated from net proceeds minus your adjusted basis, not from the offer price. Getting your proceeds estimate wrong doesn’t just cost you at closing. It can understate what you owe the IRS.
IRS Topic No. 701 covers how home sale proceeds get reported and how the primary residence exclusion applies. Many sellers who lived in the home two of the last five years can exclude a substantial portion of the gain, but investment properties, second homes, and short-hold flips generally don’t qualify.
A few practical points to keep in mind:
- If your basis is low and your sale price is high, the taxable gain can be larger than expected even after typical deductions.
- Model your net proceeds early enough to estimate a likely gain, not after the fact.
- If a taxable gain looks likely, set aside a portion of net proceeds for taxes rather than spending against the full check.
Run the tax math alongside the proceeds math, not after it.
How to Compare Competing Offers the Right Way
Stop ranking offers by price. Rank them by net proceeds, using identical assumptions across every offer on the table.
- Build one ledger with the categories above: payoff, commissions, closing costs, credits, prorations.
- Run net proceeds for each offer using that same ledger, changing only the terms that actually differ.
- Model best-case and worst-case versions of each offer, since inspection repairs and holdback terms can move the final number after acceptance.
- Check timing, not just amount. Cash at closing beats the same dollar figure deferred through a holdback or a slow-moving buyer financing timeline.
The offer that nets more, closes faster, and carries fewer post-closing conditions is the stronger offer, even if its price tag looks smaller on paper.
Run the Exact Numbers Before You Sign Anything
Sellers comparing offers by memory tend to guess low on deductions and high on their final number. If you’re also the type who buys, renovates, and resells property rather than just selling your own home, the same math applies to every deal you underwrite, and it compounds fast when you’re running more than one property at a time.
The flip profit calculator runs sale price against loan payoff, commissions, and holding costs to show what actually clears at closing, the same ledger logic covered above, applied to a deal you’re underwriting instead of a house you’re selling. Pair it with the holding cost calculator to see how carrying costs eat into net proceeds the longer a property sits before it sells. Both tools live under FLIP’s free flip calculators, and neither requires a live account to use.
FLIP itself is the operations layer that picks up after a flip is under contract, tracking budget against the original underwriting so the number on your spreadsheet matches the number at closing. It’s in early access now. Check the tools page to run your own numbers against a real deal.
Sources Worth Checking
For the tax side, IRS Topic No. 701 covers how home sale proceeds get reported. Bankrate’s explainer on calculating net proceeds walks through examples and typical deduction ranges. Investopedia’s net proceeds definition covers the formula in plain terms. For closing-day mechanics, this closing deal checklist maps out the adjustments that hit a seller’s final numbers.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What Does “Net Proceeds” Mean?
Net proceeds is the cash a seller keeps after the mortgage payoff, agent commissions, closing costs, and any credits or prorations are subtracted from the sale price.
How Much Does a Realtor Make on a $200,000 Sale?
Commission is typically split between the listing agent and buyer’s agent, and the total varies by market and by the terms negotiated in the listing agreement, so confirm the exact percentage with your agent rather than assuming a flat rate.
Do You Pay Taxes on Net Proceeds From a Home Sale?
Taxable capital gain is calculated from net proceeds minus your adjusted basis, not from the full sale price, and many primary-residence sellers can exclude a significant portion of that gain under IRS rules.
How Do You Calculate Net Proceeds?
Take the sale price and subtract mortgage and lien payoffs, agent commissions, seller-paid closing costs, and any seller credits, then adjust for prorations like property taxes and HOA dues.
Why Can a Lower Offer Net More Than a Higher One?
A higher offer price with large seller credits or repair concessions can net less than a lower offer with no concessions, since credits come out of proceeds dollar for dollar.
Recommended
FLIP runs the whole job — scope, subs, schedule and money on one record.