No W-9, No Pay: Employer Controls for 1099s on Contractor Pay
Yes, you need to issue a Form 1099-NEC to any independent contractor you paid at or above the current reportable threshold between January 1 and December 31, 2026. That threshold changed for payments made on or after January 1, 2026. The recipient copy and the IRS e-file copy are both due January 31, 2027. Before any of that: confirm you have a signed Form W-9 on file for every vendor. Payments under the threshold are still taxable income to the contractor, filing requirement or not.
TL;DR:
- Contractors paid at or above $2,000 in 2026 must receive a 1099-NEC, with the threshold increasing from $600 in previous years.
- Collect signed W-9 forms and perform TIN matching in December to avoid last-minute errors and IRS penalties.
- Payments to incorporated vendors generally do not require 1099-NEC, except for attorneys’ fees, or if made through third-party processors.
- Track cumulative payments to each contractor throughout the year to ensure thresholds are correctly identified, not just per invoice.
- Use electronic filing options like IRIS or third-party services, ensuring recipient consent for electronic delivery and timely correction of errors.
Table of Contents
- Quick Checklist: The Action Steps to Finish Before Filing Season
- Who Needs a 1099-NEC: Worker Classification and the 2026 Threshold
- Collecting W-9s and TIN Matching: Onboarding Controls That Prevent January Surprises
- Tracking Payments: Aggregation, Bookkeeping, and Voluntary Reporting
- Filing 1099-NEC: Form Mechanics, E-File Options, and Recipient Delivery Rules
- Penalties, Corrections, and Responding to IRS Notices
- State and Multi-State Considerations for Employer Filers
- Operational Controls From the Field: FLIP’s Recommended Workflows for Contractor Paperwork
- Optional Alternative: FLIP for Subcontractor Paperwork and 1099 Readiness
- Authoritative IRS Forms and Pages to Bookmark
- Sources
- FAQ
Quick Checklist: The Action Steps to Finish Before Filing Season
Filing season punishes whoever skipped steps in June. Run this order and January stops being a scramble.
- Confirm classification first. Decide contractor versus employee before the first check clears. Reclassifying after the fact is expensive.
- Collect the W-9 before payment one. No form, no funds. Store it with the vendor record, not in an email thread.
- Run TIN matching before year-end. December is the window. Catch mismatches while you can still fix them.
- Tag vendors as 1099-eligible at setup. Track running totals per payee all year, not just in December.
- Prepare and file by January 31. Anyone who crossed $2,000 gets a 1099-NEC, sent to them and transmitted to the IRS on the same date.
Miss step two and you’re chasing a subcontractor for a Social Security number in the last week of January. That call rarely goes well.
Who Needs a 1099-NEC: Worker Classification and the 2026 Threshold
The IRS decides contractor versus employee using three factors: behavioral control, financial control, and the type of relationship. Behavioral control asks whether you dictate how the work gets done, not just what gets delivered. Financial control asks who bears the risk of profit or loss on the job. Relationship type looks at contracts, benefits, and whether the work is ongoing or project-based. Get this wrong and the 1099 question becomes the smaller problem.
Once classification is settled, the threshold question is simple. For payments made on or after January 1, 2026, you must issue a 1099-NEC to any unincorporated contractor you paid at or above the reportable threshold in the calendar year. That figure will index for inflation starting in 2027. The aggregation rule matters more than the specific number: the amount totals per payee across the whole year, not per invoice or per job. Multiple smaller payments to the same subcontractor add up and may cross the threshold even if no single check did.
The threshold increased for 2026 payments compared to prior years. This is a significant operational change in 1099 reporting, and it means fewer forms for smaller vendors, not zero forms.
Exceptions to know before you build your vendor list:
- Payments to corporations are generally excluded, with one major carve-out: attorneys’ fees get a 1099-NEC regardless of entity type.
- Payments made through third-party settlement organizations, like some payment processors, may get reported on a different form entirely, so don’t double-report.
- Payments on behalf of another person or business carry their own reporting rules under IRS regulations tied to section 6041.
None of this replaces a tax professional’s read on a specific vendor relationship. It’s the baseline every employer needs before touching a spreadsheet.
Collecting W-9s and TIN Matching: Onboarding Controls That Prevent January Surprises
Get the Form W-9 signed before the first dollar moves. That single rule prevents most year-end 1099 headaches, because the alternative is chasing a contractor who finished the job three months ago and stopped answering texts.
Form W-9 collects the contractor’s legal name, business name if applicable, address, and Taxpayer Identification Number. You keep it on file. It never goes to the IRS directly, but it’s the source document for everything you’ll file in January.
The workflow that holds up under audit:
- Require a completed W-9 before releasing the first payment. No exceptions for “I’ll get it to you next week.”
- Store the W-9 attached to the vendor record, not buried in email.
- Run IRS TIN matching in December, before you start preparing forms, not after you’ve already filed and gotten a rejection.
- Resolve any mismatch immediately. A mismatched name and TIN combination is what triggers a CP2100 notice from the IRS.
- If a vendor won’t provide a W-9 after repeated written requests, document every attempt. You may need to start backup withholding at 24% on future payments, or file the 1099 with the TIN field marked as refused.
Pro Tip: Running TIN matching in December instead of January turns an unpredictable scramble into a controlled task with a fixed deadline. You find the mismatch when you still have three weeks to fix it, not three days.
Tracking Payments: Aggregation, Bookkeeping, and Voluntary Reporting
The $2,000 threshold is per payee, per calendar year, aggregated across every payment. A subcontractor paid $1,200 in March, $600 in July, and $400 in November hits $2,200 total. That crosses the line even if each individual check looked small enough to ignore.
The fix isn’t more vigilance in January. It’s catching the running total in real time, all year.
- Flag every vendor as 1099-eligible or not at the moment you onboard them, not when you’re building the 1099 batch.
- Pull an accounts-payable report by vendor monthly, not annually, so nobody crosses $2,000 without you noticing.
- Reconcile payment totals against your books at least once a quarter.
Some employers file a 1099-NEC even for contractors who stayed under $2,000. It’s not required, but it keeps the contractor’s own records clean and builds a paper trail if that relationship grows next year. The downside is minor administrative overhead for a form nobody’s required to file yet.
Filing 1099-NEC: Form Mechanics, E-File Options, and Recipient Delivery Rules
Box 1a on Form 1099-NEC holds total nonemployee compensation for the year. If you withheld backup withholding at 24% because the contractor never provided a valid TIN, that amount goes in the federal income tax withheld box. The recipient’s TIN and your own payer TIN both need to be correct, which is exactly why TIN matching happens before you fill anything in, not after.
You have several ways to actually transmit the forms:
- IRIS, the IRS’s free online portal built for smaller filers submitting a manageable number of forms.
- FIRE, the older system for filers submitting formatted electronic files, typically higher-volume filers.
- Third-party e-file services that handle both the IRS transmission and the recipient copy.
- Form 1096 as a paper transmittal summary, required only if you’re filing paper 1099s rather than e-filing.
| Filing method | Best for | Key requirement |
|---|---|---|
| IRIS portal | Small businesses, low form volume | Free IRS account setup |
| FIRE system | High-volume, formatted file filers | Pre-approved file format |
| Third-party e-file service | Employers wanting delivery + filing bundled | Service fee, vendor account |
| Paper filing with Form 1096 | Very small filers, no e-file capability | Transmittal form required |
If you deliver 1099s electronically instead of by mail, the recipient must give written consent first, and you need to tell them how to withdraw that consent. Electronic copies have to stay available to the recipient until October 15 of the following year. Skip the consent step and you’re not compliant, even if the form itself is perfect.
Penalties, Corrections, and Responding to IRS Notices
Penalties scale with how late you are and whether the IRS thinks you did it on purpose. Filing corrected within 30 days costs less than filing corrected 90 days late, and intentional disregard of the filing requirement carries the steepest penalty tier of all, with no cap.
Filing 1099s late or incorrectly is one of the more common triggers for IRS penalty notices among small employers, and the penalty schedule is tiered specifically to reward fast correction.
When you catch an error after filing:
- File a corrected 1099-NEC as soon as you find the mistake. Most correction filing happens electronically now, even for original paper filers.
- A wrong dollar amount, a wrong TIN, and a wrong recipient name all get corrected the same way: mark the corrected box and refile.
- If the IRS sends a CP2100 or CP2100A notice flagging a name/TIN mismatch, you’re on the clock. The B-notice procedure requires you to contact the payee, get a corrected W-9, and act within IRS-specified timelines.
- If the mismatch isn’t resolved after a second notice on the same payee, start backup withholding at 24% on future payments to that contractor.
State and Multi-State Considerations for Employer Filers
Federal rules don’t automatically apply at the state level. Some states adopt federal 1099 changes without any additional action from you. Others set their own reporting thresholds, require a separate state-level filing entirely, or demand a copy of the federal form even when the federal threshold wasn’t met.
The exposure grows fast if you pay contractors across multiple states.
- Check the specific state rules for every state where a payee is based, not just where your business operates.
- Confirm whether your e-file service actually transmits the required state forms, or whether that’s a manual step you still own.
- Bring in a tax professional once you’re filing in more than a couple of states. The federal threshold change doesn’t guarantee state conformity, and guessing wrong here compounds across every contractor in that state.
Operational Controls From the Field: FLIP’s Recommended Workflows for Contractor Paperwork
Paperwork problems in a flipping business start at onboarding, not in January. The fix is a rule, not a reminder.
- No W-9, no payment. Set it as policy, attach the signed form to the vendor record, and don’t make exceptions for a sub you’ve used for years.
- Flag 1099-eligible vendors at setup, so year-to-date totals build automatically instead of getting reconstructed from invoices in December.
- Run TIN matching in December. Resolve mismatches before filing season starts, and keep a written record of every outreach attempt to a vendor who’s slow to respond.
- Tie payment approvals to the vendor record. Every draw, every payment, every lien waiver traces back to the same file, so the audit trail exists before you need it, not after.
Pro Tip: A vendor record with the W-9 attached and a live year-to-date total is worth more at filing time than a folder of receipts you have to reassemble from scratch.
Optional Alternative: FLIP for Subcontractor Paperwork and 1099 Readiness
FLIP is the alternative to the folder-of-receipts approach: it centralizes vendor onboarding, stores W-9s against the vendor record, and can expose a 1099-eligible flag that tracks year-to-date payment totals as work orders get paid, not reconstructed after the fact.
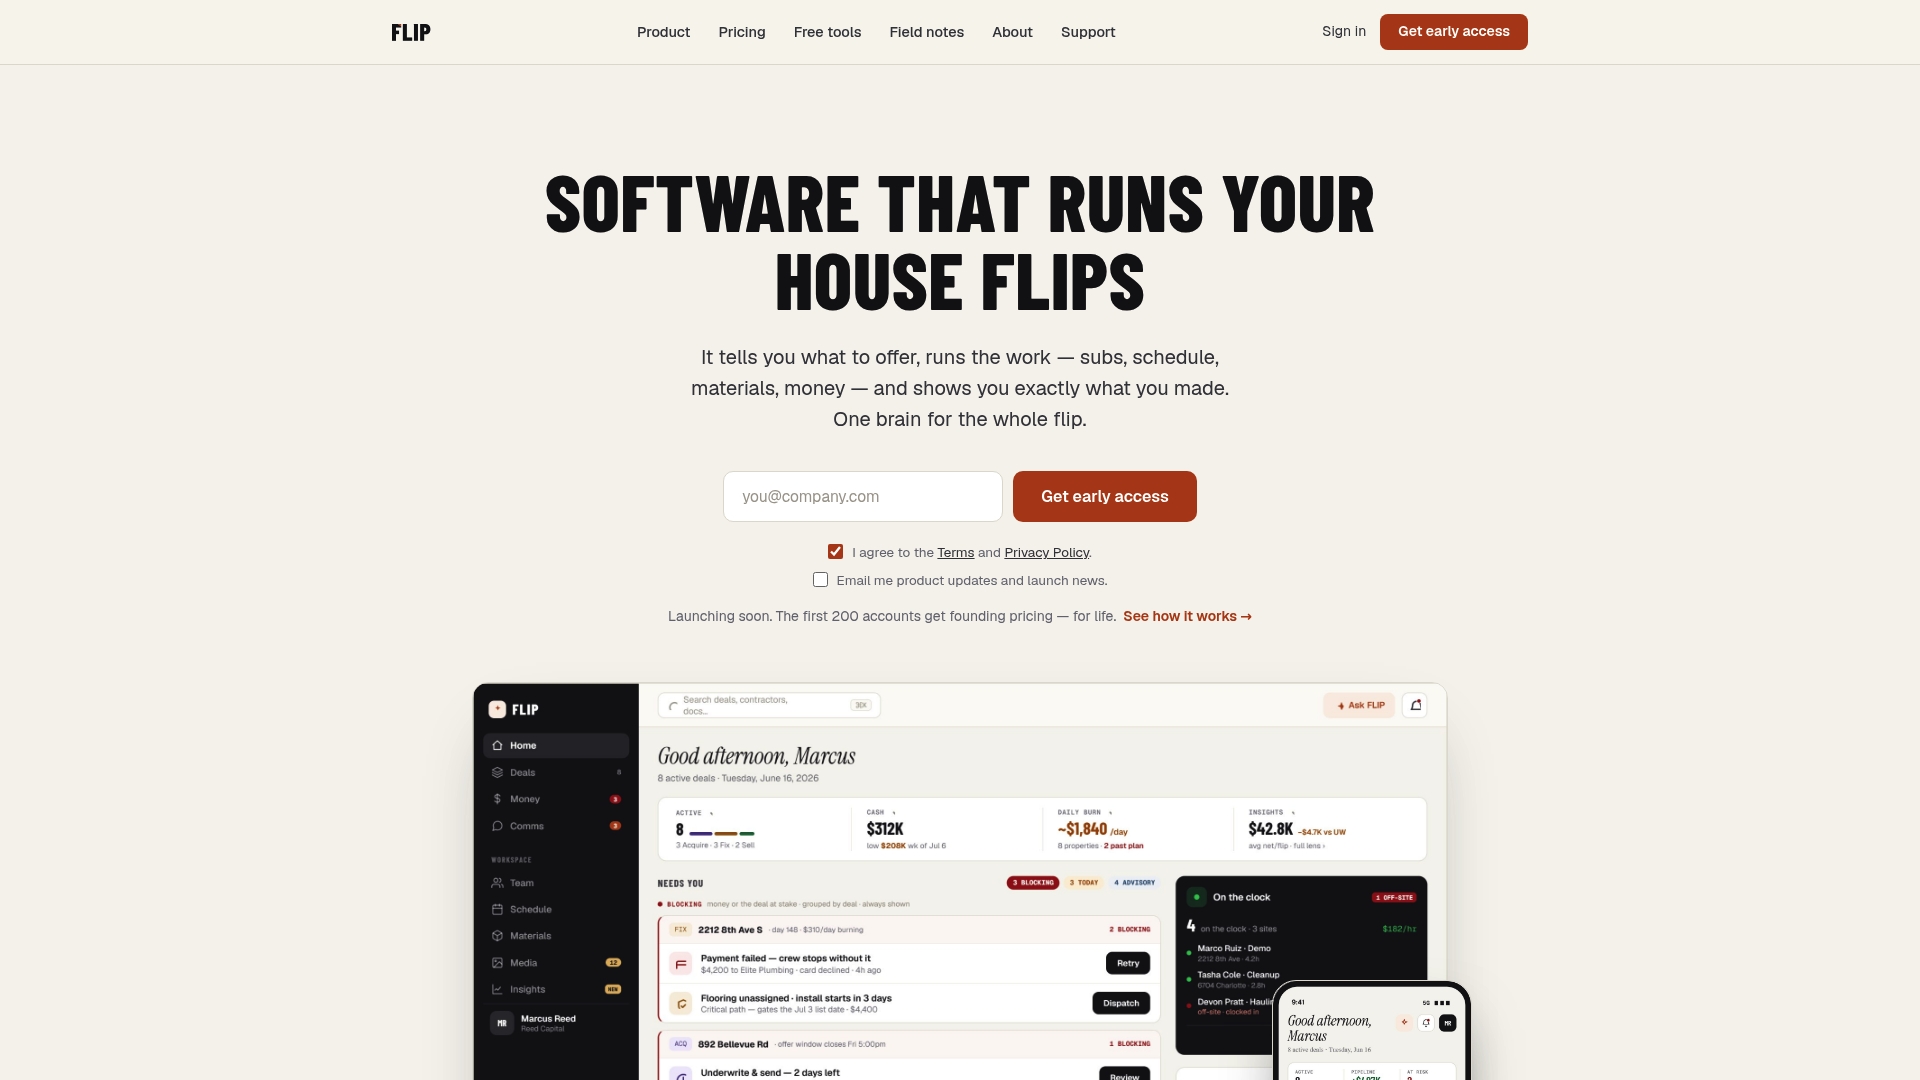
Subs and contractors log into the same app through a phone-number login, at no cost to them, which means the paperwork gets collected at the point of onboarding instead of chased down in January. Photo-verified payment approvals give every draw a record tied back to the scope of work and the vendor file. Flippers evaluating their operational setup can also run the numbers with FLIP’s free flip calculators or check a specific project’s cost exposure with the holding cost calculator.
FLIP is currently in early access, built out of the day-to-day operations at a real Southeast Wisconsin flipping business. It supports the workflow around 1099 readiness. It does not file your taxes, and it doesn’t replace a tax professional’s read on classification, thresholds, or state exposure. Check FLIP’s product overview or pricing if the vendor-onboarding side of your operation needs a system instead of a shoebox.
Authoritative IRS Forms and Pages to Bookmark
For box-by-box instructions, go straight to the Instructions for Form 1099-NEC. For the underlying filing rule and reporting logic, check Reporting Payments to Independent Contractors. Collect the Form W-9 from every vendor before payment one, and use the About Form 1099-NEC page as the quick-reference hub for deadlines and related forms.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What 1099 form do I send a contractor?
Independent contractors paid for services get a Form 1099-NEC, which reports nonemployee compensation in box 1a. It’s a different form from 1099-MISC, which covers things like rent or legal settlements.
How much tax will a 1099 contractor owe?
That depends entirely on the contractor’s own tax situation, including self-employment tax and their overall income, and it’s not something the paying business calculates or owes. The business’s obligation stops at accurate reporting and timely filing.
What are the new 1099 rules for 2026?
The reporting threshold rose from $600 to $2,000 per payee per calendar year for payments made on or after January 1, 2026, with inflation indexing starting in 2027. The filing deadline stayed at January 31 for both the recipient copy and the IRS copy.
How much does a contractor need to earn to get a 1099?
A contractor needs to be paid $2,000 or more in total during the calendar year to trigger a required 1099-NEC for payments made in 2026. Below that, the business isn’t required to file, but the contractor still owes tax on every dollar earned.
FLIP runs the whole job — scope, subs, schedule and money on one record.